MONEY: Financial planning with old memes

Sunday, October 21, 2012

http://www.businessinsider.com/the-coming-retiree-crisis-2012-10

Take Action Now To Prepare For The Great Retiree Crisis

Jeff Voudrie, See It Market | Oct. 10, 2012, 8:30 AM

***** begin quote *****

The financial planning community has largely relied on assumptions regarding equity, debt and inflation percentages that have been experienced over the last 30 years.

There are 3 problems with these assumptions:

Equity returns the last 30 years have been extraordinarily high as a result of the longest and greatest Bull market in the history of U.S. stock markets. Accordingly, many financial plans used projections that assumed equity returns of 8-10% a year.

Debt returns over the same period are equally skewed. Remember the double-digit interest rates of the 1980’s? In 1989, as a young broker, I was selling 30-year TVA bonds yielding 10%! Financial plans the last 5-10 years have used interest rate assumptions around 5-6% a year.

The scenarios that led to the historic markets the last 30 years are very unlikely to EVER be repeated in today’s retiree’s lifetime. And those who are taking distributions based on these outdated assumptions may soon run out of money.

For instance, let’s assume that someone retired 5 years ago at age 60 with a $500,000 investment portfolio. Based on financial plans popular at that time, the retiree is taking $2500 a month in distributions—money they need to maintain their current standard of living. Since the plan anticipated the ability to average a 7% return on a portfolio with close to 50% in equities, the retiree expects to be able to take those distributions and never run out of money.

Adjusting those assumptions based on what many believe resembles more reasonable assumptions going forward requires decreasing the rate of return assumption for a similar-risk portfolio to around 4% and increasing the inflation assumption from 1-2% a year to 3-4% a year (which may still be too conservative). Suddenly, the portfolio that should last forever is now projected to be exhausted in only 16.8 years! That means that the entire nest egg and what it earns cannot sustain the current withdrawal rate. Since the retiree started the withdrawals five years ago, now they are down to 11.8 years—running out of money around age 76!

***** end quote *****

Clearly, the political class has screwed up the American economy.

Pity the poor, the elderly, the middle class, those on fixed income.

Inflation is grossly understated by the “official” stats.

Are we headed to be like Europe or pre-WW2 Germany?

Clearly, everyone needs to update their financial plans.

I’ve recommended to my turkeys that they adjust their “money reserve requirements”.

Everyone better plan to work for a longer time.

— 30 —


MONEY: Tax hikes coming!

Saturday, October 20, 2012

http://www.financial-planning.com/news/How-Advisors-Can-Use-2012-Tax-Breaks-Before-They-Disappear-2681313-1.html?ET=financialplanning:e11881:34803a:&st=email

Dear Team:

I don’t see much news I can use?

  • Possibly pre-pay medical premiums (e.g., Maybe 7200$ x and y premiums; see if I can prepay z premiums?).
  • ROTH conversion rarely makes any sense (i.e., pay taxes now to maybe save them later)?
  • Take cap gains in taxable accounts (i.e., doesn’t fit with the Edelman style of investing).

Did I miss anything?

fjohn

*****

This is a recent email sent out. Recognize that if the Congress critters do nothing, which is their MO, we get slammed with a gigantic tax hikes in 1/1/13.

Don’t think there is much to do, but revolt.

–30–

f


MONEY: The falling dollar hurts real people; an ebb tide lowers all boats

Friday, October 19, 2012

http://www.mybudget360.com/us-standard-of-living-falling-us-dollar-impact-us-dollar-benefits/

Standard of living, meet falling US dollar – how a falling US dollar benefits banks at the expense of working Americans.

*** begin quote ***

There is certainly a cost to a falling US dollar. Many Americans are living the consequences of this multi-decade long trend. The Federal Reserve has only added fuel to this trend but many families are now realizing that there does come a cost to unrelenting debt based solutions to fiscal problems. Shopping at the local grocery store I’ve noticed that some items have doubled in the last few years. Fueling up is also more expensive. The issue with living on a low dollar policy is that eventually, you end up in a low wage capitalist system. The easy money slowly inflates away especially on global items. We are seeing this in the US in various arenas especially with higher education. The end result is that the standard of living for the vast majority of Americans has fallen dramatically in the last few decades.

*** end quote ***

The seems to be a basic stupidity in human beings as to the devastating impacts of “inflation” (i.e., counterfeiting by a central bank).

As an injineer, we can’t have a “standard” that varies. 

As a football fan, imagine if a yard was redefined each football season as 2% less. 35.28 inches. Easier to make a first down. Records would be meaningless. And, eventually, in 30 years, they’d play on a one inch field.

Absurd.

So why is it different for money?

In my lifetime, the “dollar”, whatever that is, has lost 99% of it’s value. Gasoline that was 30¢ per gallon was $3.75 last night. Has gasoline become more expensive? Those evil oil companies. No!!! Based on the price of silver, gas is actually ~30% cheaper. 

<<Those three silver dimes in 1960 bought a gallon of gas. Today those three dimes are worth about $6 (conservatively) to $10.50 (speculation). So either 28% cheaper or 65% depending upon your value of those dimes.>>

Why can’t “We, The Sheeple” see it?

And, in the general inflation (i.e., loss of value of the money), wages don’t go up. Those on fixed income are so screwed. And, the poor get poorer. Savings are a joke.

Also even the stock market gets “hurt”. Sure the stock prices go up, but never as much as the inflation rate. We’ve seen this in the Carter disaster. Then, stocks went up in the single digit %s, but the inflation was 25 or 30%. Hence the real value went down.

How does a tin foil hat view the world? Always price things in silver or gold. Makes it obvious.

A new men’s outfit in Rome was two ounces of gold. Today, you can buy a nice outfit for 3500$! Clothing has gotten “cheaper”.

A new car in the 60’s was 6 ounces of gold. (I know a bought a Chevy Nova brand new for 1200$). Today, 10,500$ won’t get you a new car. Cars have become more “expensive”. Gas we’ve already said has gotten “cheaper”.

What do you buy that’s changed?

Gooferment!!!

# – # – # – # – #   


MONEY: PT is less than AU?

Thursday, October 18, 2012

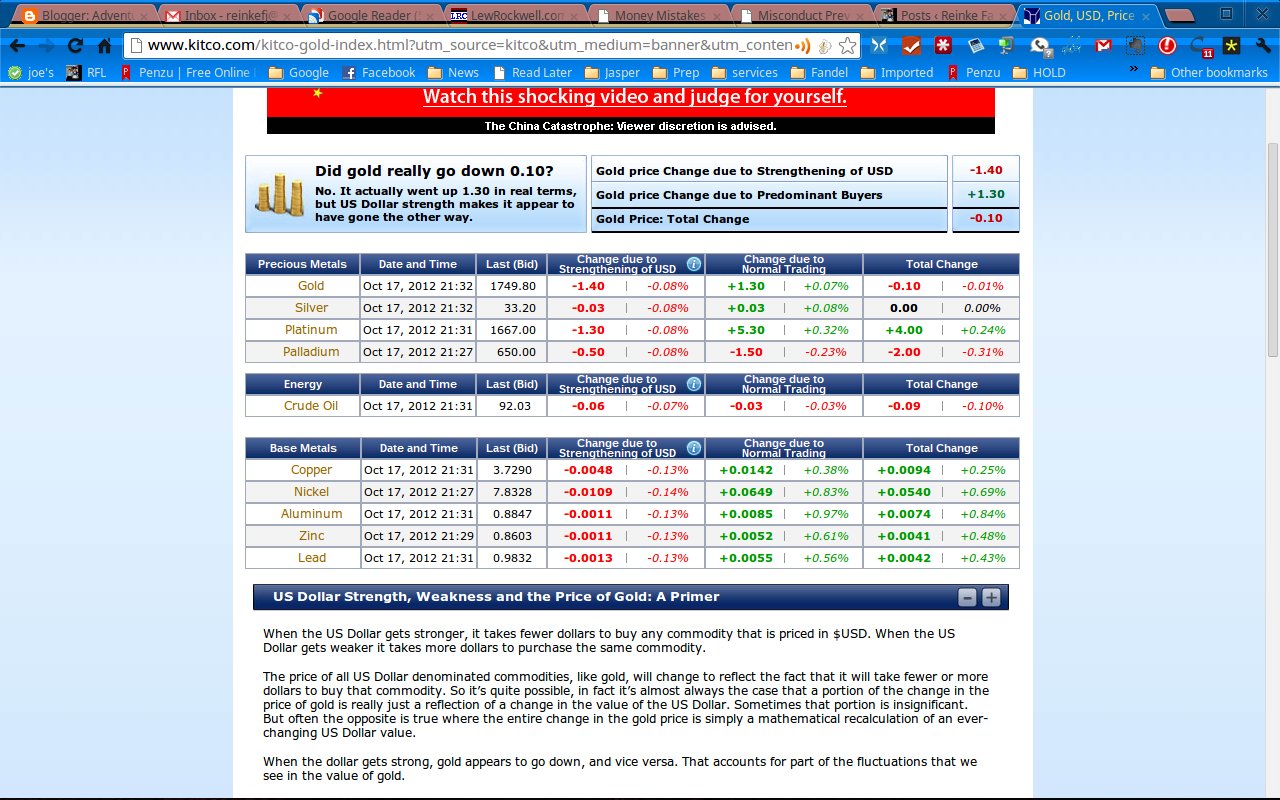
KITCO Metals quotes


Take a look at the price of platinum versus gold.

What does this signal?

Price manipulation in the commodities markets in advance of the election?

Wonder when we’ll hear about the derivative contracts that are used to move the market.

Argh!

—30—


MONEY: Commodities tell us that the politicians are lying. (What’s news there?)

Wednesday, October 17, 2012

http://www4.thedailybell.com/28133/Peter-Schiff-Riding-Into-the-Sunset-or-a-Brick-Wall

Riding Into the Sunset or a Brick Wall?
Tuesday, October 09, 2012 – by Peter Schiff

*** begin quote ***

If everyone starts to carry rolls of cash everywhere, it’s not a big leap to carry coins. A silver coin the size of a dime is currently worth about $3.50. Two could buy you lunch.

*** end quote ***

As someone, who remembers 29 cent per gallon gas — with a glass, trading stamps, and a guy to wipe the window, it’s not a far stretch to imagine a country using gold and silver coins as money.

Paper should be bank warehouse receipts. No fractional reserve banking should be permitted.

We shouldn’t let the elite effete political class define money. Money should be a weight of something. The free market will assign it a value.

In the debate Ron Paul gave a classic line about “in the Sixties, three silver dimes would buy a gallon of gas and those same three silver dimes would buy more gas now”. Still true. Even in California.

Now if you are reading this, just ask yourself: “What’s changed?”

Three silver dimes = gallon of gas in 1960’s = more than a gallon of gas in 2012.

Yet, gas is now over $3 per gallon. 5 in California.

What’s changed?

Could it be that the value of the dollar has changed? Not the value of silver or gasoline?

What’s the yardstick?

This makes the case that gasoline is actually CHEAPER now.

Argh!

And, the politicians tell us there is no inflation!

No wonder the oil sheiks are screaming like stuck pigs. They are getting robbed like the rest of us.

# – # – # – # – #


MONEY: Governments have always robbed their subjects by debasing the currency

Thursday, October 11, 2012

http://dailyreckoning.com/paper-money-despotism

Paper Money = Despotism
By Wendy McElroy | 10/08/12

*** begin quote ***

In his invaluable book What Has Government Done to Our Money? the Austrian economist Murray Rothbard addresses the strange reluctance to consider private currencies, “Many people, many economists, usually devoted to the free market, stop short at money. Money, they insist, is different; it must be supplied by government and regulated by government.” (Note: Technically, the currency is generated through a banking cartel with government support.)

History frowns upon that theory. Before the United States Mint issued its first coin in 1793, the 13 colonies were awash with an assortment of currencies that included both private and government-issued ones. Current fiscal reality also frowns on this. Privatizing zealot Martin Durkin calls the idea of government guaranteeing the quality of money “the sickest joke in economic history. Governments have always robbed their subjects by debasing the currency, but this abuse, in recent years, has burst all bounds of decency and sanity.”

*** end quote ***

Had a similar conversation this weekend with Luddite.

We were talking about “secession”.

Among the challenges that came up was “money”.

A State, that secedes, would want to abandon the “Federal Reserve Note”. If it was smart, it would use what ever the free market dictated and allow it all to float. 

Second best would be to demand gold and silver in what it collects and what it pays.

Luddite was stunned that folks might have to change money.

LOL!

Guess he’s never traveled internationally that much.

If the seceding State used gold or silver, I’d want some of that. Rather than the trash we have now.

# – # – # – # – #   


MONEY: CD rates are the answer to the wrong question

Thursday, October 4, 2012

BANKING
Is It Stupid to Save? 5 Alternatives
With low interest rates here to stay, we look at options that can beat putting money in the bank.
http://www.smartmoney.com/plan/banking/is-it-stupid-to-save-5-alternatives-1348525179055/?cid=djem_sm_WeekontheStreet_t

#####

I find it amusing when articles give financial advice without any context. No that I’m a financial guru. But at least I’d stratified my advice into some tiers:

dirt poor — you should be focusing on burn rate and “months of cushion”

poor — you should be focused on pyramid and how you establish a basis going forward

young family man — should be thinking insurance and home ownership

youngsters — save your nickels and develop 10 part time jobs

… … before you start worrying about savings rates!!!

#####


MONEY: Understanding the tax on stupidity

Friday, September 28, 2012

http://www.ricedelman.com/cs/pressroom/pressroom_detail?pressrelease.id=3268

Against All Odds

For Immediate Release
September 21, 2012

If you insist on playing the lottery, make sure you know the true risks and downsides.

*** begin quote ***

When you step outside your home, are you afraid of being struck by lightning? Of course not. You know the chances are remote.

But you were more likely to be hit by lightning twice than you were to win the top prize in the Mega Millions lottery jackpot when it paid a record $640 million recently. Indeed, you were 176 times more likely to be struck and killed by lightning than to win that jackpot, four times more likely to be killed by fireworks and nine times more likely to die from a television falling on your head.

Just so we’re clear, I’m not a big fan of buying lottery tickets. Essentially they are a tax on the stupid. Because of the infinitesimal odds against winning, you’re giving dollars to the government for nothing in return.

*** and ***

Sadly, those who spend hundreds of dollars annually hoping to become an overnight multimillionaire will never achieve the riches they seek. But if they instead placed that money into the average stock mutual fund every day for 45 years, they would indeed become wealthy.

It’s true: $3 invested every day for 45 years, assuming it grows at the historic 10% annual return that the S&P 500 Stock Index has earned on average since 1926 according to Ibbotson Associates, would be worth nearly $1 million.

*** end quote ***

An excellent and perceptive argument against the chronic lottery player.

Some folks are “lucky”. But many “gamblers” I know, even “lucky” ones, avoid the lottery in any form because they are “not lucky at it”.

Most persuasive part of Rick’s indictment is that $3 / day makes you a millionaire in 45 years!

I didn’t realize that. Wish I had 45 years ago.

I do remember some NYC bank had the adage “small leaks sink great ships” embossed on its passbook savings. Maybe it should have been “three bucks a day makes you a millionaire in 45 years”.

Do Americans save ANYTHING any more?

I also noticed today driving through a “poor  section” of town that everyone I saw was smoking. Hmmm, a causal relation?

# – # – # – # – #   


MONEY: Only spend 80% of what you make!

Monday, September 24, 2012

http://www.doughroller.net/personal-finance/5-things-i-did-in-my-20s-that-made-me-rich/

5 Things I Did In My 20′s That Made Me Rich In My 40′s
by Rob Berger
in Personal Finance

*** begin quote ***

My wife and I just sent our first child off to college, and we’ll send our second to college next year. Through all the things that go with this time of life, I’ve been very focused on teaching my children sound money management principles. And the process made me realize just how much the decisions my wife and I made in our 20′s affect our finances today in our 40′s.

Despite the headline of this article, we’re not quit-your-job rich. But we are comfortable. We have no debt other than our mortgage. We paid cash for our last car (a used Toyota Camry hybrid). We have money set aside for our children’s college education. And we are on track to retire.

So if you are in your 20′s or know somebody who is, here are five decisions that made all the difference.

Decision #1–Earned a VALUABLE degree

Decision #2–Avoided consumer debt

Decision #3–Began investing early:

Decision #4–Bought modest vehicles: 

Decision #5–Maintained good credit: 

*** and ***

If you are in your 20′s, I hope you’ll give some thought to the above as you make decisions for you and your family. Trust me, you’ll thank me twenty years from now.

*** end quote ***

Not sure if I agree with #3.

And, I’d say that “#0 — Only spend 80% of what you make!” Wish I’d known and done that. My wife taught me that one. She’s save all the bonus money, raises, windfalls, tax refunds, … and a portion of all “big” casino wins. 

(If you’re NOT lucky like me, don’t gamble.)

And, NEVER EVER play the state run lotto or numbers. It’s really a tax on stupidity.

Argh!

# – # – # – # – #   


MONEY: Don’t think your employer pays anything; you do!

Friday, September 14, 2012

Ignore taxes and benefits and anything other than the value equation.

Assume for a minute that an employee generate $100 of value for an employer.

And, that is the basis of the deal they strike.

Let’s say the employer is generous and give the employee ½ and keeps the other ½.

Employee winds up with $50.

Now lets factor in ONLY social security tax. (12.4% “split” 50/50)

Same value equation.

The $50 “earned” by the employee.

$6.20 split 50/50? 3.60 each.

So the employee gets $46.40, the Gooferment gets $6.20, and the employer retains a value of $46.40.

If to do the deal the employee has to give the employer $50 of value, then the employee has to be willing to take less.

So the employee has to be willing to take $43.80 so that the employer gets $50.

Cut through the illusion that the employer “pays half”!

The employee’s value equation is reduced by the tax that the employer pays.

Each deduction from your pay obviously you pay. But, every dollar your employer puts out on your behalf, ALSO, comes out of YOUR pocket.

Benefits are a bigger scam.

Remember that EVERYTHING comes out of your (the employee’s side of the value equation).

So any benefit that the employer “gives” you, you’re paying for.

And, for example, in the case of health benefits, the employer gets a tax deduction.

But, if you buy them, you don’t. (Yeah schedule A maybe after the % take back.)

How about life insurance? Same thing! They get a tax deduction on your money. And, that’s not deductible to you ever.

Argh!

It’s a rigged game and employees think the employer is being “magnanimous”.

Every item is like that: pension, 401k contribution, … everything has an angle that favors the employer.

# – # – # – # – #